Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
The sell-off in chip stocks is deepening today, worrying investors as market await the latest UK GDP report.
Signs of rising inflation in the US are driving concerns about the risk of interest rate hikes, and AI-linked stocks are bearing the brunt.
In South Korea today, the share index has plunged by over 8%, extending its recent losses. Chip giants (-9%) and (-10.5%) are leading the rout.
Japan's is sliding too – it's down by 4.5% in late trading.
This follows a drop on Wall Street on Wednesday, where the index fell by 1.1% and the lost 1.9%.
That includes an 11% plunge in shares, which CNBC blames on mounting concerns that enterprise spending on artificial intelligence won't justify the AI buildout.
The news yesterday that US inflation has jumped to 3.7% has alarmed traders, as it makes it more likely that the US Federal Reserve will raise interest rates soon – possibly even at the end of this month.
Further evidence of right-tail inflation risk in the US has reinforced the higher-for-longer rates narrative, with sellers emerging across risk assets and interest rate-sensitive equities coming under renewed pressure.
The breadth of price pressures across the CPI basket has been particularly concerning, challenging a market desperately in need of evidence of disinflation.
These inflation pressures will also worry policymakers at the IMF's Annual Meeting in Bangkok, which continues today ()
We'll soon learn how the UK economy performed in August, too. The latest GDP data, due at 7am, is expected to show a fall of 0.1% in the month, as growth fizzled out after a strong July.
The agenda
-
7am BST: UK GDP report for August
-
10am BST: Eurozone industrial production report for August
-
1.30pm BST: US initial jobless claims data
Although Britain's FTSE 100 share index is holding up well this morning, other European markets are in the red in early trading.
Germany's index dropped by 0.5% at the start of trading, a few minutes ago, while France's is down 0.2% and Spain's lost 0.17%,
The London stock market is open, and shares in mining companies are dropping sharply.
Copper produder (-6.5%) is leading the fallers on the FTSE 100 share index, with (-4.2%) and (-4%) close behind. That may reflect concerns that a rise in US interest rates to fight inflation will dampen growth, and demand for commodities.
However, the wider FTSE 100 index is only down 0.1%. As it doesn't include many tech shares, it is insulated from the rout in chip stocks today. Instead, 'defensive shares' such as tobacco firms, consumer goods maker (+2.6%) and hotel chain (+2.4%) are in demand.
The UK economy "surprised yet again" by growing by 0.1% in August, says , chief UK economist at :
explains that the UK's resilience story continues:
Undoubtedly, there may be some hiccups to come in the run up to year end, especially as energy prices continue to bite household incomes, and higher rates continue to drag on spending and investment.
The good news? The UK's resilience story continues. It's hard to overstate how strong the UK performance has been all year. The UK economy remains the fastest growing G7 economy.
What's more impressive? If you believe the HMRC jobs data, UK GDP growth has hit 1.8% this year in the first eight months of the year, with 95k FEWER jobs. Who said productivity growth was dead in the UK?"
Today's better-than-forecast UK growth report is good news for chancellor John Healey as he hobnobs with other finance ministers at the IMF meeting in Bangkok.
But it may encourage the Bank of England to raise interest rates as soon as its next meeting in November….
, chief economist at chartered accountants group , explains:
"While August's unexpected uptick all but confirms that the OBR will raise its growth forecast for this year from 1.1% to 1.4%, the Chancellor still faces a major Budget headache, as elevated borrowing costs eat into fiscal headroom and increase pressure for tax rises.
"These unexpectedly upbeat figures will further embolden hawkish sentiment among policymakers by reinforcing the view that the economy is strong enough to withstand a rate rise, making a November hike look highly likely."
The money markets indicate there's a nearly 93% chance tht the Bank raises rates at its November meeting….
August's growth means the UK economy continues to perform well against international rivals.
Britain had already grown faster than fellow-G7 members France, Germany, Italy, Japan and Canada in the first half of 2026, and roughly as fast as the US.
senior economist at says:
"The latest GDP figures are encouraging, with the economy growing by 0.7% in the three months to August, its strongest growth rate since May. On its current trajectory, the UK is likely to record growth comfortably above 1% this year, which would probably be enough to make it the second-fastest-growing economy in the G7.
"The UK's growth performance has been a bright spot amid a less impressive run of economic news following events in the Middle East. Business investment has been an important driver, particularly spending on ICT hardware, likely linked to the build-out of AI infrastructure. The UK still lags the US in both the scale of that investment and the boost it provides to growth, but it is making progress and remains ahead of many of its European peers.
Emeritus professor , head of economic research at accountancy and advisory firm , points out that the underlying pace of growth in the UK economy remains weak.
Responding to this morning's UK GDP report, he says:
The loss of momentum in August reflects the impact of continued inflationary pressures that have negatively impacted consumer confidence and spending.
Businesses also continue to face tough trading conditions resulting from rising employment costs and taxation which have squeezed profitability, particularly among small and medium-sized enterprises, discouraging investment spending and recruitment activity.
Over the last quarter, the UK economy grew by 0.7%, today's GDP report shows.
That's the fastest quarterly growth since the three months to May.
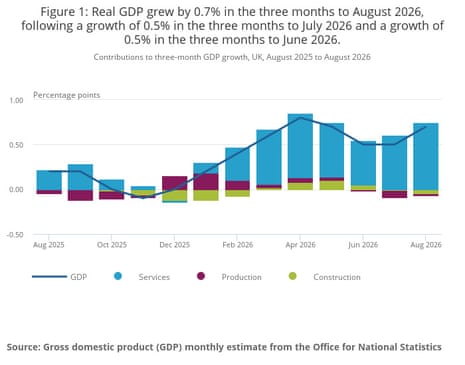
Growth over the quarter was driven by the IT sector – perhaps a sign that AI technology is starting to boost growth?
director of economic statistics explains:
"GDP growth showed further strength in the latest three months, led by the services sector, while both production and construction fell. Upward revisions to already strong services growth in June and July helped drive robust growth across the three months, despite services showing no growth in August.
"Computer programming was once again the largest contributor to growth in the three months to August. Looking at a longer-term picture, compared with the same three-month period a year ago, the increased strength now seen in services is evident not just in computer programming but across a range of business-facing industries, including legal services, research and development and advertising."
Britain's manufacturers drove the economy forwards in August.
Today's GDP report shows that the growth in August was driven by a 0.8% growth in production – including a 1.2% jump in manufacturing output.
The Office for National Statistics says this was due to growth of 5.1% in manufacture of basic pharmaceutical products and pharmaceutical preparations, and growth of 1.8% in manufacture of transport equipment.
Services (which makes up around three-quarters of the economy) showed no growth, and construction output fell by 0.2% in the month.
Newsflash: the UK economy posted modest growth in August, beating expectations!
The Office for National Statistics reports that monthly GDP grew by 0.1% in August, beating expectations of a fall of 0.1%.
That follows unrevised growth of 0.4% in July.
June's growth rate has been revised up too – to +0.4%, up from +0.3% previously.
"Markets have just had an incredibly tumultuous 24 hours, as a strong US CPI print was then followed up with mounting fears around the AI trade", reports , strategist at .
He adds:
Moreover, there's been a huge selloff in Asia overnight, with the KOSPI (-7.04%) and the Nikkei (-5.08%) both slumping, and the KOSPI even saw a circuit breaker triggered earlier given the scale of the declines.
points out that the cost of insuring the debt of some AI companies, such as has been rising – a sign that investors are nervous about leverage and borrowing levels.
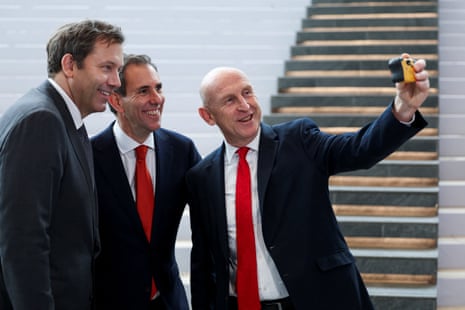
The chancellor, John Healey, has arrived in Bangkok for the IMF/World Bank meetings and spoke briefly as he entered the conference centre this morning.
He welcomed the IMF's endorsement of the UK's fiscal policy -the Fund's managing director urged the government to "stay the course" on Wednesday.
Healey said:
"I'm pleased the IMF here in Bangkok have backed our economic plans in London. They say the UK stands out on growth despite the deep economic shocks that are affecting worldwide at present.
They say Britain stands out on our plans to get to grips with the big borrowing costs by previous governments. They also say it's important to stay the path, and I will follow that as I prepare my budget in two weeks' time."
He said he would be urging fellow G7 member-countries to continue backing Ukraine; and announced £20m of UK support - alongside France and the US - for critical repairs in Chernobyl.
attended a meeting of G20 central bankers and finance ministers today, and was also due to hold discussions with Georgieva, and have bilateral meetings with the Australian, Qatari and Saudi finance ministers, and the South Korean deputy prime minister.
[NB John, it's STAY THE COURSE not STAY THE PATH that's not a thing]
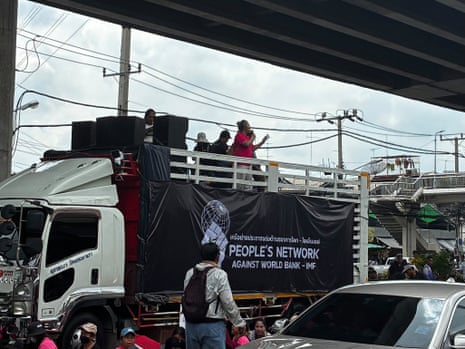
Good morning from Bangkok, where the route from my hotel to the vast Queen Sikirit conference centre where the IMF/World Bank meetings are being held was blocked by this small but noisy protest by the People's Network Against World Bank-IMF, with their friendly-looking World Bank pig.
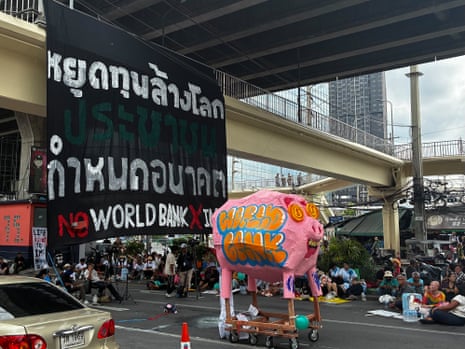
They're apparently a coalition of environmental and civil society groups who oppose IMF/Bank-backed development projects as costly and opaque.
Local media have reported scuffles, but at the time I saw them, the numerous police lined up appeared bored, rather than tense.
Good morning, and welcome to our rolling coverage of business, the financial markets and the world economy.
The sell-off in chip stocks is deepening today, worrying investors as market await the latest UK GDP report.
Signs of rising inflation in the US are driving concerns about the risk of interest rate hikes, and AI-linked stocks are bearing the brunt.
In South Korea today, the share index has plunged by over 8%, extending its recent losses. Chip giants (-9%) and (-10.5%) are leading the rout.
Japan's is sliding too – it's down by 4.5% in late trading.
This follows a drop on Wall Street on Wednesday, where the index fell by 1.1% and the lost 1.9%.
That includes an 11% plunge in shares, which CNBC blames on mounting concerns that enterprise spending on artificial intelligence won't justify the AI buildout.
The news yesterday that US inflation has jumped to 3.7% has alarmed traders, as it makes it more likely that the US Federal Reserve will raise interest rates soon – possibly even at the end of this month.
Further evidence of right-tail inflation risk in the US has reinforced the higher-for-longer rates narrative, with sellers emerging across risk assets and interest rate-sensitive equities coming under renewed pressure.
The breadth of price pressures across the CPI basket has been particularly concerning, challenging a market desperately in need of evidence of disinflation.
These inflation pressures will also worry policymakers at the IMF's Annual Meeting in Bangkok, which continues today ()
We'll soon learn how the UK economy performed in August, too. The latest GDP data, due at 7am, is expected to show a fall of 0.1% in the month, as growth fizzled out after a strong July.
The agenda
-
7am BST: UK GDP report for August
-
10am BST: Eurozone industrial production report for August
-
1.30pm BST: US initial jobless claims data